Too frequently, Nigerians across the country suffer severe hardship due to the scarcity of petroleum products, especially premium motor spirit (PMS). The most recent episode of PMS scarcity lingered through the tail end of 2022 into the first quarter of 2023. Despite the government’s assurances that there were enough petroleum products in stock, the scarcity persisted amid a poor electricity supply. Businesses and households had to choose between standing long hours in queues to get a rationed quantity of PMS or depending on erratic power supply from the national grid. Last year, the national grid collapsed multiple times causing total blackouts in many parts of the country. Petrol-fired generators are a common source of independent power production for households and businesses in Nigeria.
Public transportation is one of the hard-hit sectors during each episode of scarcity: private cars, commercial vehicles and motorcycles combine with individuals to create a desperate mob seeking to get ahead to buy petrol. As the scarcity lingered, the cost of a litre of petrol rose uncontrollably to N500 per litre in some parts of the country – the official petrol price moved up to N185 from N175 per litre. Soon, there were black market dealers reselling petrol at a premium across major cities in Nigeria. This would have cost-push implications for general price levels. The cost of petrol, through transport costs, is a driver of inflation in Nigeria.
What are the issues?
There are several factors responsible for this anomaly. From inadequate refining capacity to challenges with distribution, bunkering, systemic corruption, and political instability, the challenges facing Nigeria’s petrol sector are multifaceted and deeply entrenched. But I reviewed these issues from the economic dimensions of price, supply and demand.
Unstable price
Nigeria is an oil-producing nation but has no functional refinery. Therefore, it imports most of its refined petroleum products. This has exposed the country to the uncertainties of international crude-oil pricing. This is amplified in this period of global energy crisis occasioned by the Russia-Ukraine conflict. As the prices of imported refined products go up, the pump price of petrol and other by-products go up; it passes through transport costs to have a cost-push impact on the general price level. Also, the national debate on subsidy removal creates market uncertainties that mar price signals. Nigerians are now looking forward to how the new Dangote refinery would impact the domestic price of petrol.
Faltering Supply side
The lack of adequate investment in the downstream sector has made it difficult to meet the local supply requirements. Over the years, there has been a paucity of new investments in refining, distribution and storage facilities due to policy inconsistencies. Although the new Petroleum Industry Act 2021 was expected to address this, the impact of proper implementation is not yet strong enough to lure private capital to the sector. No doubt we have seen some projects coming up, but the scale needed to bridge the supply gap in the shortest possible time is still missing.
The 4 sick sisters which are government-owned refineries have been out of operation for several years. Nigeria has had to import refined products from abroad after exporting crude oil. This situation exposes the economy to exogenous shocks in the oil market. Yet, with a combined capacity to refine 445,000 barrels of crude oil per day, the four local refineries continue to incur annual operational costs without refining a single barrel of crude oil. According to an audited statement of the Nigerian National Petroleum Cooperation (NNPC) Limited, the refineries did not record any revenue in 2021 but incurred a comprehensive loss of N69 billion.
Corruption in subsidy management makes the entire business chain less transparent. While the landing cost of petrol is currently estimated at N400/litre, the Federal Government (FG) mandates marketers to sell at N185/litre through its subsidy programme. However, the dwindling revenues vis-à-vis foreign exchange shortfall make it difficult for the FG to sustain the subsidy on PMS consumption. The FG has mulled over the removal of subsidies over the years. It is apprehensive of the citizens’ negative reactions as there could be some immediate adverse economic implications especially for the bottom of the pyramid if not properly coordinated. Subsidy payments in the sector have been fraught with monumental fraud over the years. Several organizations were indicted for receiving payments for petrol not supplied yet no one has been punished. With prices ranging from N195 to N400 in different parts of the country a few months ago, one wonders if the subsidies are still in effect.
The thriving business of smuggling refined products also stokes petrol scarcity in Nigeria while indiscriminately increasing the government’s subsidy bill. It is estimated that about 30 million litres of petrol per day are smuggled across Nigeria’s borders to neighbouring countries. A major incentive exists for smuggling due to the significant price disparity between Nigeria and its neighbours. While petrol was selling for N175/litre in Nigeria before the current fuel scarcity, it sold for between N400/litre and N500/litre in border countries like Benin and Niger Republics. The high price differentials create room for smuggling to these neighbouring countries.
Bloating Demand side. What is increasing the demand?
In 2020, the NNPC reported an anticipated increase in demand for petroleum products in Nigeria from 15.1 million metric tonnes (MT) to 17.3 million MT, an increase of 14.6%. Curiously, there was no correlated corresponding increase in economic activities during this period. However, some developments are responsible for the increasing demand most of which have not attracted much attention in public discourse.
The erratic electricity supply situation in Nigeria is endemic. It has one of the greatest grid instabilities in the world. The country has struggled with poor power supply for years, often caused by generation and transmission problems. The national grid collapsed multiple times last year alone. As a result, many Nigerians depend on power generators. These generators are mostly powered with PMS which aggregately increases the demand for PMS by both businesses and households. Without commensurate supply, scarcity often ensues.
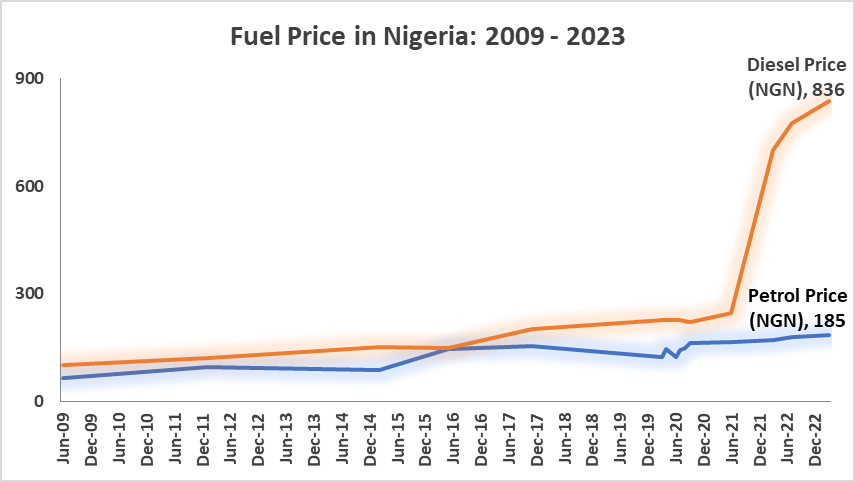
After the deregulation of the diesel market in 2009, the price rose gradually from about NGN90 in September 2009 to about NGN300 in December 2021, then steeply spiked to NGN800 as of November 2022 (see the figure below). Since diesel is used by many commercial enterprises, this sharp increase has driven up the operating costs of many businesses, prompting diesel users to seek alternative sources, especially PMS and solar. The net implication is a rise in demand for PMS.
Petrol-for-diesel fuel switch has not been given much attention. Fuel switching simply refers to the course of changing the fuel source used for energy-consuming activities. This can involve switching from one type of fossil fuel to another or from fossil fuels to renewable energy. Fuel switching is often done for environmental reasons, such as to reduce greenhouse gas emissions, but it can also be driven by economic factors, such as fluctuations in the price of different types of fuel. Since the hike in the price of diesel following the deregulation, PMS has become relatively cheaper due to the retained consumption subsidy from the government. Consequently, large households and businesses inevitably switched to PMS to power their backup generators. Many users abandoned their diesel generators for petrol-powered ones thus increasing the demand for petrol.
The graph shows a spike in diesel prices in March 2022 at the height of the energy crisis induced by the Russian-Ukraine war. Source: Nigeria Bureau of Statistics
So, are there any possible solutions?
The effects of the fuel shortage on Nigerians are numerous. Economic activities are usually paralyzed and the burden is mostly borne by people at the bottom of the pyramid. It slows down business activities as prices go up and both businesses and households tend to postpone spending decisions until prices normalize. At other times, it leads to mass protests which can get violent and lead to the destruction of properties and the loss of lives. But for how long can this continue? I discuss some ways out of the woods below.
Concerted efforts must be made to attract private investments in the downstream business. Moving from a heavily regulated regime to a deregulated private sector regime is a challenge. Perhaps the PIA is not getting the needed publicity, especially in the international scene to attract foreign capital flows. Increasing investments in the local supply chain and improving capabilities will surely translate to improved supply. All eyes are on the Dangote refineries.
The development of the Dangote Refineries and other modular refineries.
The Dangote Refinery is expected to eliminate the importation of petroleum products; saving about $50 billion in annual imports. The refinery, which was commissioned on 22 May 2023, by the outgoing President Buhari a week before his handover to the incoming president-elect, Bola Tinubu shows the national significance of the Dangote refinery. This single project could drastically improve the supply chain bottlenecks, cut import bills, engender foreign exchange accretion and reduce the pump price of fuel. The advantages and benefits of local refining could create the grounds for subsidy removal without harshly jeopardizing welfare – if well-coordinated.
The government should also take steps to refurbish the existing refineries in the country by allowing private investments. The process of commercialization and privatization of these assets, like the telecom sector, to credible investors could get us out of the woods. If the local refineries become fully functional, Nigeria could easily become a net exporter of refined products.
Improving the electricity supply, especially to residential and commercial hubs will go directly into reducing the demand for petrol. After all, residential demand for petrol-to-power is a major factor driving up petrol consumption. By increasing electricity generation and enhancing transmission and distribution systems, petrol demand would be reduced by more than half. Again, if there was any time that renewable energy needed to be given more attention, that time is now.
Is subsidy ever a good idea? Despite the position of the Brenton Woods institutions, western countries still apply subsidies to support particular sectors, especially at critical times. For instance, many countries in Europe increased subsidies on public transportation at the peak of the recent global energy crises conditioned by the Russian war in Ukraine.
For Nigeria, the government could create conditions to boost the local production of petrol and redirect subsidies to welfare-enhancing areas of the economy. One way to do this is to open up the sector to credible private investments in oil refining, increase production and supply capacity, and reduce demand for refined products by boosting electricity generation and reducing transportation demand for petrol by creating a healthy public transport system). The subsidy may then be applied to public transportation. To remove subsidies without backlash, we must reduce residential PMS demand and moderate prices by improving grid electricity supply.
The way forward
The deregulation of the downstream sector remains a potent and lasting solution to petrol scarcity, in the hope that it attracts investments to the sector to boost supply. The government must revamp or privatize the existing refineries as it simultaneously encourages investments in the downstream sector. We need to have smaller pockets of Dangote refineries across the countries, and the goal should be to become a net exporter of refined petroleum products over the next 10 years.
In the long term, there must be a shift in paradigm in our energy security strategy if we are to avoid energy crises in the future. We must adopt multiple approaches like diversifying the energy mix through private sector investments, modernising energy infrastructure to include smart grid solutions and green buildings and promoting energy efficiency measures aimed at reducing demand. Simple solutions, such as using energy-efficient appliances in buildings will go a long way.
No thanks to the wrong political and economic choices of the last decades, Nigerians have been plunged into multidimensional poverty. Nigerians are facing scarcity on many fronts: food, Jobs, energy, and recently, naira scarcity due to the attempt by the Central Bank to demonetize the economy. We are running on empty. The incoming administration must be innovative on all fronts to steer the local economy out of the slow economic growth. Efforts must be concerted to tackle energy scarcity and poor energy infrastructure to support SME growth and enhance the quality of life in Nigeria. While countries are gravitating towards green, clean energy alternatives, we are still grappling with distributing dirty fuels. Nonetheless, energy assurance is critical for the development of any nation. Economic advancement is hardly possible without access to sufficient energy.
The distribution and administration of Covid-19 vaccines are creating unpalatable challenges. On one hand, high-income countries (HICs) are circumventing COVAX, a coalition established to coordinate the equitable distribution of COVID-19 vaccines globally, to enter direct purchase agreements with big pharmaceuticals. The result is the inequitable access to vaccines to low-income countries (LICs) and the continued spread of the mutating virus. On the other hand, anti-vaccination propaganda has caused tremendous vaccine hesitancy and wastage across the world even more so in the HICs where they have stockpiled more vaccines than necessary.
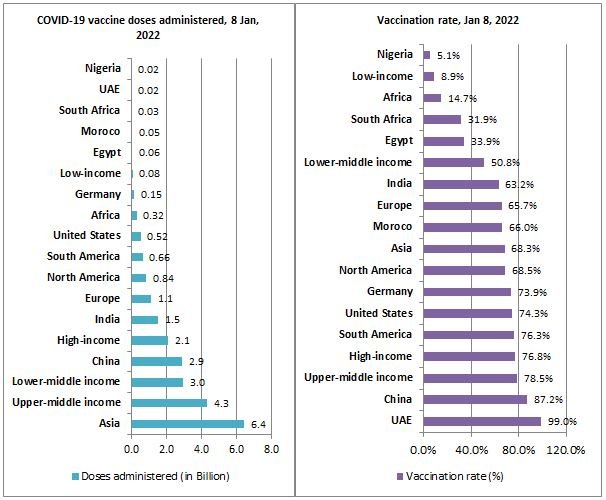
The WHO vaccination data shows that over 17.2 billion vaccine doses have been procured globally. According to data from Our World in Data, about 9.4 billion doses have been administered – representing 54.7% of procured vaccines. As of January 8, 2022, total administered doses represent 59.1% of the global population, of which 49.93% are fully vaccinated and 9.15% are partially vaccinated. HICs and upper-middle-income countries (UMICs) have achieved comparatively high vaccination rates (see figure 1). Figure 1 shows that HICS and UMICs have administered at least 20 times more vaccines than in LICs. Countries such as China, UAE, the US, and Germany have higher vaccination rates than LICs and Africa.
Figure 1: COVID-19 Vaccine doses administered. Source: Our World in Data
In Africa, the vaccination rate is low compared to other regions – 14.7% (see figure 1). Vaccination in Africa accounts for only 3.3% of vaccines administered globally. The Africa Centre for Disease Control data shows that 58.7% of total vaccines supplied were administered as of 5 January 2022. The total vaccine doses supplied was about 546.7 million doses – roughly 3.1% of global vaccine procurement. As of January 5, 2022, the share of fully vaccinated people was 9.6%; the share of partially vaccinated was 5.1% while booster shots administered was 0.35% of the population. The data shows that Africa lags in terms of total vaccination rate compared to America (72.4%), Asia (68.3%), and Europe (65.7%).
At less than 15% one year after vaccine rollout, LICs show a very slow vaccination rate. This poor vaccination performance is due largely to countries in Sub-Saharan Africa such as Burundi (0.05%), D.R. Congo (0.3%), Chad (1.7%), South Sudan (2.1%), Eritrea (no vaccination), and other countries such as Haiti (1.1%) and Yemen (1.9%). Whilst LICs struggle to meet vaccination targets, high-income countries (HICs) are surpassing their targets, delivering vaccine booster shots against mutating variants of the virus and vaccinating children. Throughout 2021, more booster doses were administered in HICs than the vaccine doses in LICs. This phenomenon has been described as vaccine inequality. Vaccine inequality is due mainly to vaccine nationalism – a situation where national governments exploit bilateral agreements or export restrictions to secure vaccines in advance for their nationals to the detriment of other countries.
In the early stages of vaccine production, many HICs and middle-income countries (MICs) entered bilateral and multilateral arrangements with pharmaceutical companies to secure surplus quantities of vaccines for their population. The result is an inequitable distribution and access to vaccines and an overall inability to collectively tackle variants of the Coronavirus. The World Health Organization (WHO) warned against such a nationalistic approach to vaccine distribution and formed COVAX in alliance with GAVI, the Vaccine Alliance, and the Coalition for Epidemic Preparedness Innovations (CEPI). COVAX was envisioned to be the primary distributor of COVID-19 vaccines globally to guarantee fair and equitable distribution and access to COVID-19 vaccines for every country in the world. Within COVAX, the Independent Allocation of Vaccines Group (IAVG) serves as an independent referee for a needs-based allocation of vaccines. However, rich nations largely sidestepped COVAX, hoarding doses for their populations and cutting deals directly with LICs and MICs.
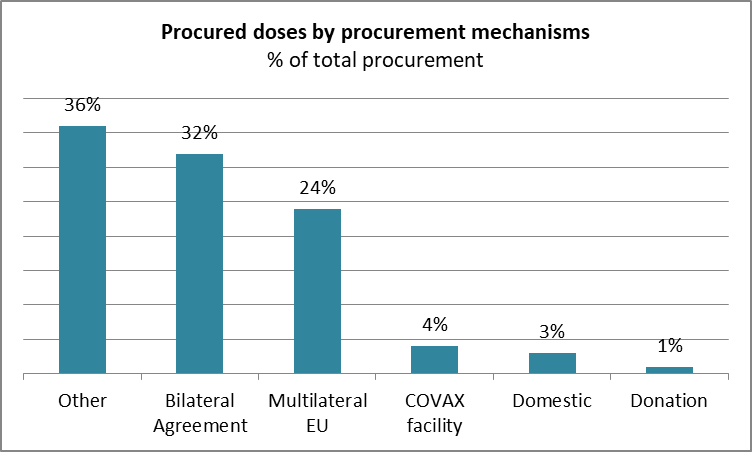
The optimistic target for COVAX was to achieve 20% vaccine coverage through COVAX-secured doses by the end of 2021. So far, COVAX has distributed less than 10% of the total vaccine administered globally. According to WHO data, vaccine procurement is largely done under bilateral (32%) and multilateral (24%) agreements. COVAX facilities account for only 4% of purchase agreements (see figure 2). This underlies the vaccine nationalism and inequality arguments, leaving redistribution to vulnerable LICs as an afterthought. COVAX now mainly coordinates and redistributes vaccines to LICs.
Figure 2: Share of vaccine procurement mechanisms. Source: WHO COVID-19 dashboard
Vaccine doses not administered are vaccines wasted
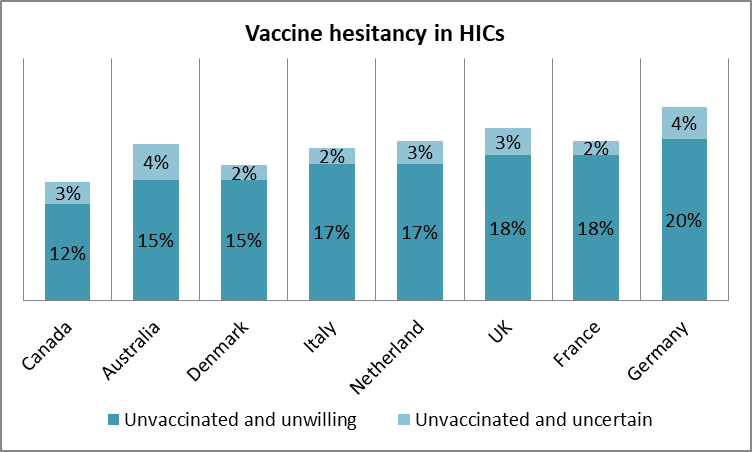
For many HICs, vaccine wastage is partly due to the unwillingness to take the vaccines amongst other issues. In the US, over 15 million doses were wasted since March 2021; France, theUK, and Germany also forecasted high volumes of wastages. By taking a nationalistic approach to vaccine procurement, many countries did not consider the hesitancy that would ensue (see figure 3). Vaccine hesitancy, underlined by the short shelf-life of the vaccines as well as other vaccine administration and policy issues resulted in the observed high vaccine wastages in many countries.
Figure 3: Survey on (un)willingness to get vaccinated in HICs. Source: Our World in Data
While for HICs, the stockpiling of vaccines for national use and the eventual wastages poses a moral question, for LICs, the story is different. In LICs, vaccine wastage is due to a combination of factors including the short time frame left on donated vaccines, logistical issues and poor infrastructure to deliver vaccination, administrative bottlenecks, vaccine preferences, and hesitancy as well as vaccine racketeering. For instance, in D.R. Congo and Nigeria over 1.7 and 1.1 million doses of vaccines respectively were destroyed due to expiration. Local media reports that the donations were made only a few weeks before the expiry date. As a result, underlined by other logistical and infrastructural bottlenecks, only a fraction of the donated vaccines could be administered. In Kenya, corrupt officials are diverting vaccines for auction at $30 – $50; in other instances, vaccination cards are issued for travel purposes to those not vaccinated.
Nonetheless, juxtaposed with the huge vaccination gaps globally, vaccine wastage is an irony. The excess in the global north is the lack thereof in the global south. A WHO report showed that ninety-eight countries have not vaccinated 40% of their population, and in Sub-Saharan Africa, the vaccination rate is less than 15%. Even though vaccine production has improved (21 approved vaccines) since the rollout in January 2021, vaccines are not distributed fairly and equitably. For instance, less than one in ten health and care workers (HCW) have been fully vaccinated in the African region while four in five have been vaccinated in 22 mostly HICs. Meanwhile, 15 times as many booster doses are currently being administered globally as are primary doses in LICs.
Going forward
COVAX has been working to improve distribution and reduce wastage (to acceptable limits ~5%). To minimize wastage in LICs, COVAX now tries to access the country’s needs for vaccination vis-à-vis their absorptive capacity to distribute and administer vaccines at a level that minimizes wastage. In October 2021, WHO released the Strategy to Achieve Global COVID-19 Vaccination by Mid-2022 with an expanded target to achieve 40% total population coverage by the end of 2021, and 70% total population coverage by mid-2022. Even though the target was not achieved in 2021, with improvement in vaccine production in 2022 and an extensive collaboration amongst HICs, COVAX, pharmaceutical companies, and LICs, it may be possible to surpass the target by the end of 2022.
Currently, governments and firms are resorting to strict vaccine mandate to increase vaccination (for example, Austria, Ecuador, MTN, Citi group). But such strategies can cause massive pushback protests which reverse the gains and increase infections. Therefore, it may be better to be more tactical, use communication and counter-narratives to diminish the spread of anti-vaccine theories. The use of key local stakeholders and trust institutions such as religious houses and family heads may be effective. Vaccine officers must be informed to give vaccination and then register all individuals who present themselves for vaccination. In Nigeria, people have been denied vaccination because they were not pre-registered or scheduled.
In 2021, FutureProofing healthcare initiative launched a health policy index known as the African Sustainability Index. 18 African countries were studied and ranked across six vital signs. Nigeria ranked 14th with a total score of 44 over 100. The country’s low performance is a reflection of the poor state of the health sector and inadequate budgetary allocations to improve the sector. For instance, Nigeria spends 3.89% of its GDP on the health sector, a figure that is proportionately lower than the 5% suggested by the World Health Organization (WHO). Nine years to the 2030 sustainable development goals, Nigeria is still far behind in universal health coverage (UHC). According to the World Health Organization, monitoring UHC means focusing on two key aspects: i) the proportion of the population that can access quality health care and ii) the proportion of a population that spends a large amount of household income on health. This categorizes the focus on UHC into access and financing. In this article, health finance will be the Focus while the third article in this series will discuss access to quality care.
Based on the African Sustainability Index ranking, Nigeria is the 4th lowest country in health finance, with a score of 36. This indicates lapses in Nigeria’s current health financing model, primarily based on households’ out-of-pocket expenses, compared to the tax, health insurance, and donor funding-based models predominant in other environments. According to the WHO, for a healthcare financing model to be considered efficient, the population should not spend a large amount of their income on healthcare. Unfortunately, this is not the case in Nigeria.
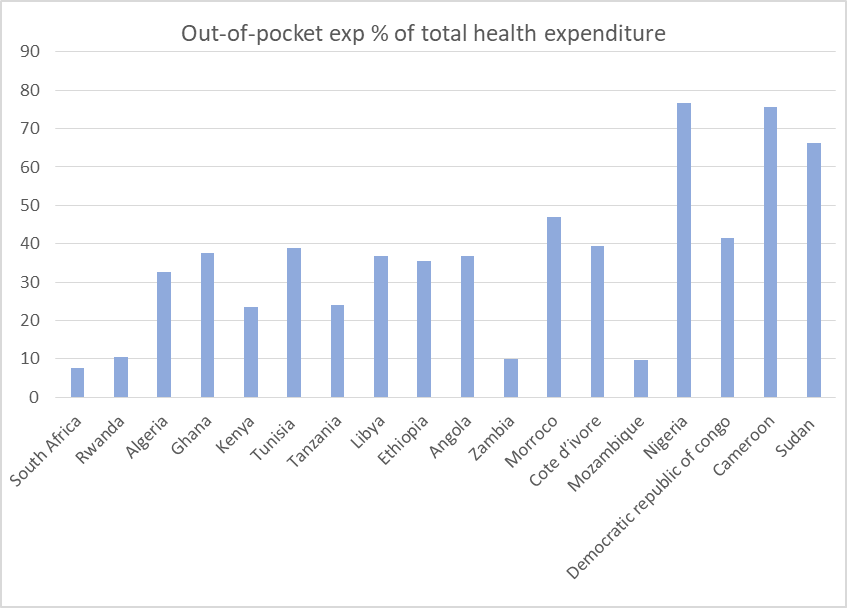
Health care in Nigeria is financed by mostly the out-of-Pocket model. About 69% of Nigerians finance their healthcare needs from personal savings or income. Regardless of their income, they have to pay for any health service rendered to them as well as the cost of drugs. The graph below shows the percentage of total health expenditure financed by out-of-pocket payment in the 18 African countries evaluated by the Future-Proofing initiative. The countries in the graph are placed according to their rank in the financing index. The graph shows that Nigeria has the highest level of out-of-pocket payment amongst the 18 countries. Although the graph does not show a clear relationship between out-of-pocket payment and position in financing, we can observe that the countries with an out-of-pocket rate above 50% are in the lowest rank of financing.
Source: World Bank data, 2018
Out-of-pocket payment is a hindrance to health care given that over 40% of the population live below the country’s poverty line of $0.8 a day (World Bank, 2020). In fact, with the high rate of inflation, an additional 7 million people have been pushed below the poverty line according to a World Bank report in 2021. For instance, the cost of a complete malaria medication is $3 which is approximately 1500 naira. The hospital consultation fee varies between $2 and $50 depending on whether the hospital is private or government-owned. These costs, combined, outstrip the minimum wage of $53 and therefore beyond the reach of many. Government-owned hospitals which is usually the cheaper option would have been the solution to this dilemma but the financial burden is still higher than the estimated poverty indicator. The remaining 60% of the population living above the poverty line are not better off, they still grapple with high medical bills.
Recently, a growing number of the population is being financed by the National Health Insurance. The National Health Insurance Scheme (NHIC) was implemented in 2005 to pool health risks at the national level. The scheme is designed in a way that every member of the society irrespective of economic status would be covered. However, as of 2019, only 5% of the population were enrolled in the scheme. One reason for the low enrolment rate could be because the government has not made it mandatory for individuals in the informal sector. With Nigeria’s huge informal sector (about 70%), one can most certainly say that the scheme is inherently not mandatory. Even within the formal sector, some private employers do not provide basic health insurance coverage for their staff. Another factor that could contribute to the low enrollment rate is unawareness on the part of the populace. Some Nigerians, especially the uneducated populace are unaware of the insurance scheme. Some of those who have heard may not fully understand its implications and advantages over out-of-pocket payment. Hence, they may decide not to enroll in the scheme. In addition, apathy for government-run programs could contribute to the general low coverage in over 10 years.
Though relatively small, another source of healthcare funding in Nigeria is donor finances. These funds come from Non-Governmental Organizations, international organizations, faith-based institutions, and private donors. The donations often come in the form of medical equipment and consumables, drugs, blood banks, vaccines, and funds for hospital construction or renovations. These funds are often targeted at the poor and vulnerable and major disease-burden such as Malaria, HIV, Tuberculosis, Hepatitis, Cancer screening, and eye treatment. In as much as these donor programs have their impacts, they are generally inadequate and not readily available to cover the (infrastructure) financing gap in the health sector.
There is an urgent need for Nigeria to create a pro-poor health financing plan to bring about equity in the country’s health care system. This will entail more government involvement in health financing. The first step could be to optimize budgetary allocation to the health sector. In the Abuja declaration of 2001, African countries were urged to allocate 15% of their budget to the health sector. In the past 2 decades, Nigeria’s average allocation to health care is 4.67%. Eliminating financial barriers to quality and effective health care is another option to be explored. With the high poverty rate, risk pooling methods could be an effective method of eliminating the financial barrier. Insurance and tax-based financing methods are the top risk pooling methods of health financing. Although Nigeria already has the NHIS, more sensitization should be carried out to create awareness and encourage mass enrolment in the scheme. In all, effective health care finance is the first action towards revamping the entire health sector.
Until his usurpation on September 5, 2021, Alpha Condé has been the president of Guinea, a West African nation since 2010. President Condé was a human rights professor and activist who fought nearly four decades for democracy in Guinea before his victory at the polls ten years ago. He became the first democratically elected leader after 52 years of dictatorship in Guinea. President Condé is 83 years old and had completed what should have been his last term in office in 2020 according to the constitution at the time.
Last year, the Guinean parliament held a referendum that amended the constitution and extended the presidential term limit to two terms of six years per term—a slight shift from the previous 5-year term. The referendum was held in March 2020, a few months before the general elections in October of the same year. President Conde sought a leeway in the ‘timely’ constitutional amendment to contest a third term in the election. A media report noted that President Condé had hoped that the new constitution would allow him to restart his presidential tenure. This way, he would be looking at another 12 years in office.
Shortly after the referendum, Condé was re-elected president after winning 59.5% of the total votes at the polls in October 2020. He was subsequently inaugurated for a third term (or by his calculation, the first term under the new laws) in November 2020—despite the allegations of electoral malpractices and violence leveled against him by the main opposition, Cellou Dalein Diallo and other contestants.
Guineans have endured a history of authoritarian regimes since their independence in 1958. Condé was the first publicly elected president. It might be interesting to review the socio-economic conditions in Guinea over the last 10 years.
Socio-economic conditions under Condé
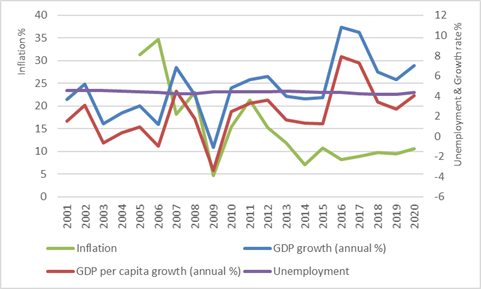
Guinea under Conde has not been as bad (in terms of economic indicators) relative to previous authoritarian regimes. Several economic indicators seem to have improved over the last 10 years—compared to the 10 years before. For instance, Guinea’s gross domestic product (GDP) has been rising following the transition to democracy in 2010. The average growth since Condé’s democracy (2010 – 2020) of 6.2% is higher than that of the previous 10 years under dictatorship – 2.7%. Last year, GDP was $15.68 billion – a 131.1% and 82.4% increase from 2011 and 2016 levels. Figure 1 shows how the growth rate spiked in 2010 and 2016 after Conde’s (re)election in the respective years. Despite the pandemic, GDP recorded a positive growth of 5.2% in 2020. The impressive growth is mostly due to the performance of the extractive sector.
Guinea has significant mineral resource endowments such as bauxite, iron ore, gold, diamonds, and limestone among others. The US Geological Survey data in 2021, reported that Guinea was the second-largest producer of bauxite (82 million tons in 2020) with a proven reserve of 7.4 billion tonnes representing 24.6% of world reserves. According to the African Development Bank’s outlook report 2021, activities in the mining sector grew 18.4% in 2020 from 8% in 2019. World Bank data shows that the rents from minerals have been rising—from 4.45% (2001) to 10.2% of GDP in 2018. Mining accounts for 35% of GDP. China is a major trading partner.
In the labour market, World Bank data shows an average unemployment rate of 4.4% since 2001, lower than the Sub-Saharan (SSA) average of 6.1%. Youth unemployment is however slightly higher at 5.4% (SSA: 11.9%). Agriculture is the main employer of labour accounting for 63.9% of employment. Like other indicators, the price level has fluctuated through the years since 2005; there has been some moderation since 2012 (see figure 1). Last year, inflation was 10.6% (2019: 9.5%).
Figure 1:GDP growth rate and Inflation 2001-2020 | Source: Word Bank data
In summary, Condé’s administration had some positive impact at least on the macroeconomy. It implies that Conde’s democratic regime outperformed the dictatorship regime before him. However, it does not imply that Condé’s regime was the best it could have been. For instance, Guinea remains one of the poorest countries in the world with a per capita GDP of less than US $1000 in 2020. A recent report by the World Food Program showed that 55% of the population live below the poverty line – a sharp increase from 36.1% in 2012. The outbreak of Ebola and Covid-19 worsened living conditions as food insecurity for households was at 21% while 24.4% of infants suffer severe malnutrition. World Bank shows that only about 36% of the population live in urban centres and 50.1% of the urban population live in slums. The exchange rate to the dollar has depreciated 91.3% since Condé took office in 2010. Currently, one US dollar is worth over 9,100 Guinean francs. Guinea is import-dependent as imports of goods and services account for 42.3% of GDP in 2019. Thus, one could argue that economic growth during Condé’s administration was not so inclusive.
In the Human Development Index (HDI) report 2020, Guinea ranked 178 out of 189 – the same rank it had in 2011. Guinea’s HDI of 0.477 in 2019 is below the average of 0.513 for countries in the low human development group and below the average of 0.547 for countries in Sub-Saharan Africa. HDI is a measure for assessing long-term progress in three basic dimensions of human development: a long and healthy life, access to knowledge, and a decent standard of living.
Post-Conde Guinea: Autocracy or democracy?
Since independence from France in 1958, Guinea has been through three dictatorship regimes that ended only after the demise of the dictators. So far, regime changes have been effected through coups. Alpha Condé must have been aware of this pattern and perhaps intended to remain in power for as long.
President Condé, like many African freedom fighters in his time who became dictators, seems to dwell on a certain entitlement (akin to the divine right of Kings) to potentate themselves in power. These autocrats claim to embody a mission only they have the vision to accomplish, clinging unto power, taking out opposition, and suppressing dissent. This entitlement seems to come from the struggles and sacrifices they underwent for the emancipation of the people. The longer they remain in power, the harder it is for them to relinquish it. By altering the constitution to suit his agenda, Condé envisioned at least another 12 years in power, but by raising the budgets of the presidency and parliamentarians at the expense of the civil servants, Condé bit more than he could chew.
Mamady Doumbouya, leader of the palace coup, was a close ally of Condé and the leader of the special forces. Like Condé, he is from the Malinke ethnic group – a fact that diminishes any perspective of ethnic rivalry. Colonel Doumbouya was a legionary in the French Army before returning in 2018 to lead the Special Forces Group in Guinea. Doumbouya was close to government officials as the leader of the special forces; it was, therefore, easy for him to execute a coup. Doumbouya, in his address to the public, claimed a sense of duty to the people was the reason behind the action to halt the authoritarian inclines of President Conde. Even though he restates his commitment to return to civil rule. it is still uncertain how the transition would be conducted. Therefore, the socio-political future of Guineans remains hazy at this point.
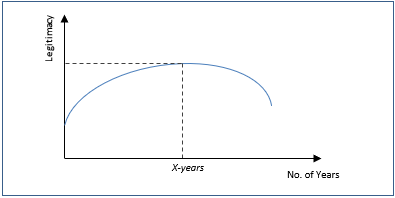
Nonetheless, Doumbouya has not acted differently from putsch leaders throughout history. Typically, putschists intend to change the status quo citing gross misconduct and corruption as the basis for their actions. But a coup is a shock to the political economy and is never an acceptable method of regime change. The international communities intervene by threatening sanctions, demanding a transition to civil rule. But because the putschists are aware of the consequences of their actions – trials or exile – they avoid this by holding onto power, ensuring a semblance of stability, and gradually winning the legitimacy of the people. The longer the putschist seizes authority, the harder it is for him to relinquish it, and the more acceptance or legitimacy he gets as things douse over time (see figure 2). Then he transitions into a democratic rule and the cycle of quasi-democracy continues.
Figure 2: Simple model of putschist legitimacy (Author’s idea)
The question is, how should coups be looked at in the future? Should the international community view palace coups differently? Are palace coups necessary, progressive in the light of prolonged, stubborn dictatorships? Would the outlook be different if a coup is justifiable and the putschists complete a handover process to civil rule? Can coups be justified? What is the implication of such a stance on authoritarian stability elsewhere? What is the situation in the Gambia, Zimbabwe, Libya, and other countries where coups have taken place? What are the alternatives to remove an authoritarian leader who has potentate himself beyond the constitutional limit? Doumbouya seems to enjoy support from Guineans: should the opinions of the citizens matter in such cases?
Coups are supposed to be moribund but seem to be gaining application in recent times. In 2021 alone, Mali and Niger have had attempts at coups; and in Chad, after the death of Idriss Deby Itno, the Chadian Army installed his son, Mahamat Deby as the interim leader. Other recent examples include Sudan (2019), Zimbabwe (2017), and outside Africa, Myanmar in 2021. Coups were common methods of regime changes in many African countries in the years after independence. It has become critical to revisit the implications of coups for regime changes, especially under authoritarian rule.
At the 2021 African Health Agenda International Conference (AHAIC), the FutureProofing Healthcare Initiative launched the Africa Sustainability index. The index is a data-driven policy tool that aims to measure the healthcare situation of 18 African Countries. These 18 countries were assessed based on 6 vital signs upon which a total score was obtained as well as an overall rank. The 6 vital signs examined are access, financing, health status, innovation, quality, and wider factors. Nigeria ranked 14 out of the 18 countries evaluated, with a total score of 41 over 100. South Africa, Tunisia, Morocco, Algeria, and Ghana were ranked in the top 5 while Nigeria, Cameroon, Angola, Sudan, and the Democratic Republic of Congo ranked in the bottom 5. All 18 countries were also ranked based on their performances in the respective vital signs. Nigeria’s best ranking was 6th under the Innovation vital sign, while the worst ranking was 17th under the vital sign Health quality. The general performance in the innovation vital sign was however poor as Nigeria ranked 6th with a score of 38.
Nigeria’s performance in the Sustainability index is not impressive and begs to question whether growth measures in Nigeria are merely quantitative. To put things in perspective, Nigeria has a GDP of USD 400 billion, the largest in Africa, but ranked among the least performers. Meanwhile, South Africa, Algeria, Morocco, and Ghana that ranked in the top 5 on the index are among the top 10 GDP in Africa, suggesting some correlation between GDP and performance in the African Sustainability index (or better still, healthcare infrastructure). However, Nigeria’s performance defies this intuition. How does a nation with such economic strength perform abysmally in a health index?
Many factors explain the distortion from GDP to poor healthcare delivery as captured in the health index. For instance, low health sector spending to GDP of less than 4% (global average is 8.8%); low budgetary allocation to the health sector to increase the supply of critical infrastructure or low health workers per capita amongst others are some of the challenges in the health sector. In the Abuja Declaration of 2001, heads of state of the African Union countries pledged to allocate 15% of their annual budget provisions to improve the health sector. According to a report by dRPC, in those 20 years, Nigeria allocated only 4.7%, on average, to the health sector – the highest allocation of 6.08% was in 2012. In 2020, allocation to the Ministry of health was 4.05% (from 3.83% in 2019) – a marginal increase despite the pandemic. Only Rwanda and South Africa have the 15% benchmark as of 2011; Nigeria is apparently off track at 4.52% in 2021.
The role of institutional factors constraining health sector performance can not be overlooked. Some institutional factors that stymie health sector performance directly and indirectly include:
Weak Institutions: Over the years Nigeria has set up various institutions and reforms in the health care sector. For example, in 2004 the National Health Insurance Scheme (NHIS) was established to tackle the challenges to healthcare access and financing at the household level. Nigeria’s performance on the Financing vital sign implies that the NHIS has not been very effective. For instance, the NHIS is largely not mandatory; and that weakens its effectiveness especially in the informal sector. Consequently, insurance coverage in Nigeria is still at less than 5%. In 2018 76.6% of current health expenditure in Nigeria is still out-of-pocket. A robust scheme and implementation framework are necessary to ensure the effectiveness of institutions, policies, and reforms to achieve a far-reaching impact on society.
Political instability: Insecurity, terrorism, and violence create an unsafe and tense environment for all sectors in an economy including health. Nigeria has an average score of -1.8 on the Political Stability index calculated from 1996 to 2019. The political Stability index range from -2.5(weak) to 2.5(strong). For comparison, South Africa and Tunisia have an average value of -0.15 and -0.27 respectively for that same period. With civil and political unrest, health infrastructures are destroyed. Qualified health care personnel are often discouraged or scared of providing services in conflict-prone areas. This creates a wide disparity in access to healthcare. Often, the international community intervenes with voluntary workers such as the Doctors without borders and Red Cross.
Corruption: Transparency International defines corruption as the abuse of entrusted power for private gain. This means the misappropriation of funds and resources meant for a particular public good. Nigeria ranked 149/180 in the corruption perception index with a score of 25/100. For Comparison, South Africa and Tunisia both ranked 69/180 with a score of 44, while Cameroon and Angola ranked 15th and 16th in the African Sustainability index ranked 149/180 and 142/180 respectively in the corruption perception index. The NHIS is a regulator and an operator which is in contravention to the Act stipulating that it should function as a regulator with defined roles. Also, poor supervisory activities create leeway for the hospitals and Health Maintenance Organisations (HMOs) to exploit subscribers who, in most cases, have limited information about the workings of the system.
What does this situation mean for our race to Universal Health Coverage (UHC) by the year 2030? According to the World Health Organization (WHO), Universal Health Coverage is a situation where all individuals and communities receive the necessary healthcare and treatment at a rate affordable to them so they do not undergo financial hardship. This means that for a nation to achieve UHC, they have to ensure that quality healthcare is available to all individuals irrespective of economic class. This concept was mooted by the world health assembly in 2005 and adopted as the 8th target of the Sustainable Development Goals (SDG) goal 3.
The Sustainability Index provides a clear insight into Nigeria’s lapses, calling for urgent policy and action-driven responses. The six vital signs examined in the index exposes thematic policy areas that enable Nigeria to achieve UHC by 2030. This article is the first in a 3-paper series to address some thematic areas of healthcare based on the 6 vital signs captured in the index. For this purpose, the 6 vital signs will be grouped into two thematic areas namely, Healthcare Financing and Healthcare delivery/access. The subsequent series will examine broadly, the two groups.
The previous year 2020 was unusual. The Coronavirus pandemic was a major headwind, and its effect would linger in many developing countries like Nigeria. Governments are not certain to see significant improvement throughout the year 2021 despite the intervention programs. In Nigeria, the EndSARS campaign in the last quarter of 2020 caused a gaping fissure to the foundations of national politics. As a result, varying levels of tensions have been experienced through 2021. Open incidences of robbery, kidnapping, terrorism, political and ethnic suspicion are a few.
Politics affect economics. Over the last 15 years, security crises in the Southsouth and Northeast have thwarted growth and prosperity in Nigeria. As the polity quakes, businesses struggle. The declining output and rising unemployment combine to limit the alternatives available to households even as inflation erodes the value of their savings. The political economy is unstable. Therefore, it is important to analyze the outlook for the rest of the year and examine the implications for businesses and investors looking to make decisions.
I refer to ‘Boyonomics’ as the ideas of Henry Boyo, a Nigerian who has persistently contested the monetary framework of the Central Bank of Nigeria (CBN) since the turn of the millennium. Boyo’s ideas build on the condition in the foreign exchange market where the CBN is the single monopolist. The CBN captures the dollar revenues of the state, converts at a unilateral rate against the Naira, before disbursing to the arms of governments, MDAs and Bureau de Change (BDC). This is equivalent to minting of naira notes (naira flood). Because the dollar revenue which has been captured by the CBN via its monopoly stance creates dollar scarcity, there is a constant devaluation pressure against the naira relative to the dollar. So to ease the pressure on the naira following the naira flood, the CBN intervenes – in the money market – with a ‘mop-stick’ by exchanging promises-to-repay in order to clean up some naira liquidity. This monotonous routine has been the operational framework of the CBN that Boyo vehemently criticizes. He has endured cursory attention – if not outright disregard – by the relevant authorities. He proposed a system that issues dollar certificate to the statutory beneficiaries with which they would offer to buy Naira in the open market such that it would be dollars chasing naira – the currency in demand gains value. But does it translate to value for the naira?
Weaknesses in the Logic
‘Boyonomics’ may not translate to increased value for the naira, rather to correct valuation of the naira at higher exchange rate! For clarity, take the currency as a tradable good paid for with goods/services. Offering a currency in the open market – to compete – implies that it has some values driving its demand. The naira is mostly backed (indirectly) by the extractive industry which is the major foreign exchange earner, but the sector is also the base of the global production value chain; and since naira is not the currency in trade, the value derives from the foreign reserves. It becomes glaring that the naira, beyond the territorial bound in which it is a legal tender, is not as worthy as the digits inscribed on it. This implies that the statutory beneficiaries, who bear these dollar warrants, negotiating from a position of strength, would demand more naira for each dollar under the liberal framework, and the banks, tempted to increase their stock of valuable dollars, would comply! Hence, under the liberalized foreign exchange market, the correct naira valuation would go under at the mercy of the dollars; and the economic woes of devaluation – eroded purchasing power, deplete foreign reserves and stagflation – would lead to suicides and revolution.
Again, assuming the representatives of the statutory beneficiaries are sincere, they would recognise that the critical short supply of infrastructures requires dollar expenditure to close: they would therefore develop preference for higher dollar balances. This implies that only the dollar sum enough to meet the naira denominated recurrent expenditures would be offered in the foreign exchange market. On the private sector side, major exports are extractive based, industries require foreign input – implying that we depend largely on imports for processed goods. All these, denominated by our population make up huge dollar import bills which take tolls on the naira value.
Why the CBN may not float
DollarDebts: generally, developing countries are not able to borrow in their domestic currencies; and infrastructural gaps imply that they require huge dollar borrowings to buy foreign technologies to minimize gaps. These liabilities are denominated in foreign currencies whereas assets are denominated in naira. In the event of shocks, a depreciation in local currency could have a devastating balance sheet effect that dwarfs the assets side (in naira) relative to the liability side (in dollars), crippling the entire financial system. Also, it becomes even more expensive in terms of naira to repay foreign debts.
Credibilityof the CBN: ensuring price stability is a statutory responsibility of the CBN. A credible central banker would want to stick to announcements about inflation targets. Therefore, the CBN, in a given period, sets a target on inflation under a loss minimization program. But because economic agents are rational, they would form expectations and engage in contracts which make the initial policy announcements of the monetary institution sub-optimal. Therefore, the central authority, in order to increase welfare (employment) along the Philips curve, deviates from announcement, creating surprise inflation. The implication here is that sustained inflation may not be the result of irrational policy decision of the central bankers but reflects their inability to commit to policy announcement due to the rational expectations of private agents. This means that the exchange rate volatility in a float system has a pass-through effect on inflation and interest rates which challenges the credibility of the CBN to stick to rules on inflation target.
Dollarization: floating the exchange rate would lead to massive devaluation of the domestic currency as we saw in the last attempt by the CBN to liberalize the market in 2016/2017. Foreign goods would become more expensive, inflation bolts in: as the naira loses value, importers would develop preference for (increasingly) scarce dollars so as to reduce the transaction costs of exchanging currencies. This would weaken even more the naira fiat, making way for the dollar as the currency in trade, superior to the naira. If this is the case, it weakens the ability of the CBN to use monetary instruments. There is the argument about the counterbalancing effect of devaluation which increases exports revenues via the price and quantity effect such that devaluation means well if the Marshall-Lerner condition holds. But are we a net exporter by balance of trade?
In conclusion, initial devaluation and uncertainty in real exchange rate bear significant output costs via reduction in investments. However, the essence of this argument is not to discredit the efforts and ideas of the man in almost twenty years, but rather to glorify his persistence with an objective response based on the principles of economics. It is possible for the CBN to run simulations based on the idea, followed by a trial depending on the results of the simulation. He deserves recognition, if not an award.
For a developing country, debt accumulation is inevitable for national governments. Government spending is typically financed by government borrowing – externally and domestically – and by raising taxes. However, it is equally vital to have a sustainable debt management framework so as to avoid over-borrowing. National and sub-national governments must incorporate some kind of inter-temporal framework in their borrowing strategy such that consumption today does not mean liability for tomorrow’s generation.
In Nigeria, the Debt Management Office is the institution saddled with the responsibility of managing the nation’s sovereign debts. Periodically, it conducts stress tests to ascertain the sustainability of the debt stock against the prevailing macroeconomic environment and the scenarios in the domestic (debt) market.
The last Debt Sustainability Analysis conducted in 2017 by the DMO adopted the latest version of the joint World Bank/IMF Debt Sustainability Framework for Low-Income Countries which provides indicative debt thresholds that reflect the quality of a country’s policies and institutions. It is based on the World Bank/IMF’s Country Policy and Institutional Assessment (CPIA) index ranking which classifies countries into one of the three policy performance categories: Weak Policy (CPIA<3.25); Medium Policy (3.25≤CPIA≤3.75) and Strong Policy (CPIA >3.75), and applies different indicative debt thresholds, depending on the performance category. Along with such countries as Ghana, Mozambique, Ethiopia and Sierra Leone, Nigeria is classified as a medium performer on the CPIA index with a score of 3.41.
The 2017 DSA included a stress test for the economy under three scenarios: the baseline scenario which hinges on assumptions of the annual budget and the medium-term expenditure framework (MTEF) 2018-2020; the optimistic scenario anchors on the optimism of the Economic Recovery and Growth Plan (ERGP) with a target growth rate of 4.80% in 2018 and 7% by 2020; while the pessimistic scenario assumes continued shock to the foreign exchange earner – crude oil – at less than $30pbd, deterioration in the external balance and depreciation of the domestic currency.
Total Public debt stock (H1 2019)
National debt
2018
2019
Diffrence
%change
Total Public debt (USD ‘bn)
73.2
83.9
*10.7
14.62
External Debt (USD ‘bn)
22.08
27.16
5.08
23.01
Domestic Debt (NGN ‘trn)
12.15
17.38
5.23
43.01
Domestic Debt (USD ‘bn)*
51.12
57.74
5.62
10.99
Table 1 Nation debt 2018 – 19
However, since the GDP growth rate has hovered below 2 per cent behind the ERGP optimism of 4.80%, but global oil price has hovered around USD60pb, and the naira exchange rates have been stable at N359/USD1; it may be objective to evaluate based on the baseline scenario since the scenarios in the other extremes have not been experienced.
As of June 30 2019, the Debt Management Office (DMO) reported that the debt stock (both national and sub-national) stood at N25.7 trillion (USD83.9 billion)—this represents a 14.6 per cent increase from the preceding year. Of this total, domestic debt accounts for 67.6 per cent (= N17.38 trillion), while external debt standing at N8.32 trillion (USD27.16 billion) accounted for 32.38 per cent.
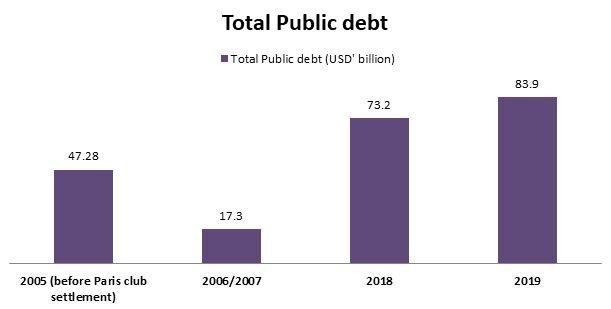
In 2018, the Debt Management Office (DMO) proposed an extension of the borrowing threshold from 19.39 per cent to 25 per cent. However, with the addition of N10.7 trillion in 2019, Nigeria already surpassed the 25 per cent threshold (see Table 1). Figure 1 shows that since-after the Paris club debt write off, the nation’s public debt stock has risen by over USD65 billion – more than twice the debt written off. The DMO also adopted a strategy to increase the ratio of domestic to foreign debt as a cushion to external (foreign currency) shocks. Table 1 shows, however, that the rate of change of domestic debt is lower (11 per cent) in terms of the foreign currency than in domestic currency (N43.1 per cent). This would be due to the exchange rate effect. Should the DMO revise or revisit its debt strategy?
Figure 1 Total Public debt as of June 2019
Sinking Funds
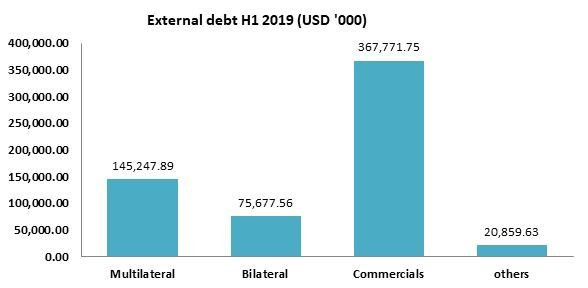
In the first half of 2019, the total amount of external debt servicing and interest payment on domestic instruments amounted USD 609.56 million and NGN800.11 billion respectively. These values are 2.2 per cent and 4.6 per cent of their corresponding total. Commercial papers and Eurobonds took 62.2 per cent of the total debt service funds while bilateral debts got the least – 3.4 per cent in Q2 2019.
Table 2 External debt H1 2019
For domestic debts servicing, FGN bonds claimed more than half of the total interest repayment in the first half of 2019; whereas FGN savings bond had the least with NGN658.54 million. From the table, most of the repayments were done in the first quarter of 2019 valued at NGN610.3 billion – representing 76.3 per cent of the total. And the FGN bond took NGN 480.85 billion.
Table 3 External Debt H1 2019 (USD’ 000)
External Debt H1 2019
Debt servicing
Q1 2019
Q2 2019
Q1 % of total
Q2 %of total
H1 2019
Multilateral
79,397.93
65,849.96
22.23%
26.10%
145,247.89
Bilateral
67,099.39
8,578.17
18.78%
3.40%
75,677.56
Commercial/E-bond
210,759.58
157,012.17
58.99%
62.23%
367,771.75
others
20,859.63
8.27%
20,859.63
Total
357,256.90
252,299.93
100%
100%
609,556.83
Table 4 Domestic Debt H1 2019
Int. on instruments
Q1 N’bn
Q2 N’bn
H1 N’bn
NTBs
120.92
45.71
166.63
Treasury Bonds
6.25
6.25
FGN Bonds
480.85
128.99
609.84
FGN Savings Bonds (N’Mn)
347.92
310.62
658.54
FGN SUKUK
8.17
7.85
16.02
FGN Green Bond (N’Mn)
718.53
718.53
Total
610.28
189.83
800.11
Conclusion
The year 2019 has been an interesting time. Macroeconomic indicators are not impressive: inflation is above 11 per cent, GDP growth less than 2 per cent, unemployment is high above 25 per cent and debt and debt servicing continues to hover over the bars. Increased government presence in the debt market would crowd-out private sector investments and matters would be debilitating. Recently, the Central Bank of Nigeria restricted the purchase of its OMO bills to banking institutions and Foreign Portfolio Investors (FPI) in a bid to re-channel funds away from risk-free assets to real sector investments. This is expected to moderate yield environment and reallocated resources to growth sectors. However, monetary institutions have to be strategic going into the New Year to hedge against external shocks and other fundamental uncertainties.
Not all statistics are worth losing sleep over. Some are just for the informational content. The home-ownership rate is one such: it is a measure of the proportion of people who live in their own houses. It indicates the strength of mortgage market and at best, a measure of aggregate prosperity. When it is low, it implies that something has to be done to increase prosperity – not home-ownership per se – in the expectation that prosperity would bring the wealth and motives to acquire homes. However, at some point in our development path, we took the wrong approach towards increasing the level of home-ownership. The government, instead of investing in housing, conducted ‘fire sales’ of public lands to the highest bidders, increasing the relative scarcity of land and its prices. Soon, everyone wanted to own lands, it had become popular as the ‘best investment’ irrespective of its high capital-output ratio. Private individuals flooded the housing market. The government eventually exited the market as it became difficult to regulate.
Today, the effects of this unstructured deregulation include illegal sales, land grabbing, collapse of urban planning, rise in squatter settlements, unhealthy competition for lands, uncontrolled factor pricing, cost-push inflation, and rising housing deficit. These made other public infrastructure – water, sewage system, and transportation – necessary for urban planning almost impossible to develop. This approach to increase the rate of home-ownership does not reduce the rate of homelessness, rather increases it.
There is a housing deficit of about 17 million. It would take the production of one million units per annum over a 20 year period to close this gap. But overall annual fulfilment is 100,000 units and a corresponding deficit of 900,000 units which carries a potential cost of US$ 16 million. The mortgage market is somewhat labyrinthine with 57 players, but mortgage financing to GDP is 0.58% (South Africa, 31%), home-ownership is 24% (Kenya, 73%). Mortgage conditions are stringent: interest rates are as high as 20% and a 25% down payment on an average mortgage size of US$ 18,000 – in country where 87 million people live below US$ 1/day. The focus should be eradicating extreme poverty not increasing home-ownership.
Presented with evidence of market failure, the visible hand of government is necessary to restore equitable distribution and social optimum in the housing market. But governments too have failed.
A number of state governments have attempted mass housing schemes: it is typically a few blocks of bungalow houses built in remote locations, deserted and often unliveable to those for whom they were intended. And when these governments realize their failures, they enter into a quasi-partnership with government compradors who connive with other individuals, in the guise of estate developers, to off-take the lands being sold out by government ministries and local communities under shady negotiations – with no pretension to transparent market process. These pseudo-developers go on to build luxury houses for themselves and the upper class. No consideration for the vast poorly-housed lower class. Ogun state is a classic case: the government and communities are off-loading the lands to churches, private developers and foreign businesses in a fate of competition with Lagos state, ignorant of the current challenges Lagos state faces. They are losing the opportunity as a sparsely populated state to initiate integrated city development.
So while these estate developers continue to build for the top 1 per cent that could afford home-ownership and already own estates, nobody builds for the ordinary man. A subtle paradox ensues: a simultaneous development of luxury estates and slum estates; whereas the former is largely unoccupied, the latter is overcrowded. The results of markets is not always optimal: no wonder while there are slum cities to revamp, scarce resources were rather directed towards building a new luxurious Eko-Atlantic city despite the number of unoccupied apartments in Ikoyi, Victoria Island and the environs. It was only recently that we realized that these empty buildings served other purposes as cash vaults to hide away stolen monies. This partly explains why rental prices are downwardly rigid in these environs where there is a glut of albeit, luxury homes.
Housing, like education and health is a critical sector in which the government cannot laissez-faire. The high capital-output ratio in housing investments implies that unchecked markets would not yield socially optimum outcome. The visible hand of government is necessary both as a player and regulator to steer the market to desirable outcome. Housing is a major part of household consumption and savings motives in developing countries. Therefore, improving housing conditions would have positive implications for standard of living.
Concluding remarks
Sadly the housing production model continues to be about luxury homes even though it is not working! The diaspora city plan of the Federal Housing Authority to build estates for Nigerians living outside of Nigeria is a case of government betrayal of the majority of Nigerians living in Nigeria with no decent roof over their heads. Government needs to return to the market: they need to increase the percentage of total land stock in the government’s possession even if it means revoking certain land titles. They need to provide proper incentives to local authorities, housing associations, private establishments and community organizations that have the resources and can endure the long-term risk-return nature of housing investments to produce standard rental units at affordable prices. Housing units could be built and then sold apartment by apartment in which case the overall assets still remains in public ownership, allowing therefore for integrated maintenance and urban planning. This was the Jakande model in 1983 Lagos state. These sorts of collaboration and coordination are necessary to correct the market distortions and provide affordable homes for Nigerians. However, the rhetoric needs to be changed: everybody cannot be homeowners. Therefore, there should be provision of a minimum standard of housing unit for life-starters and those who cannot afford luxury home-ownership.
I believe I grew up at a time that saw the last plenitude of quality products in Nigeria. I remember my brothers would jest: “revere that –Scanfrost– fridge before opening it, it’s older than you.” It was the same for the National TV, the SMC ceiling fan, the Kenwood turntable and other home appliances. These devices lasted over a decade without repairs. These products were from Europe and America. Chinese products were thought of as inferior. Then, few individuals could do importation businesses. Titles like “importer-exporter”, “general merchandise” and “international” connoted status in markets and social unions. All that soon changed.
Today, over 18.7% of imports are from China, and it is no coincident that a significant portion of import-goods are inferior products. In fact, in a regular shop, you are typically first offered a substandard item as nearly all original items have their substandard version in competition. Even pharmaceutical products are not spared. The dealers exploit the information asymmetry to create imminent Lemon problem in the import-goods market: fake products crowd-out original products. It is better to pay the minimum price and get the minimum quality than to pay the maximum price and get the minimum quality instead of the maximum quality. Interestingly, the dealers operate brazenly in most markets across the country, they are not in hiding. The war against piracy and watered quality seem to have eluded the regulatory agencies in their duplicative forms – Standard Organisation of Nigeria (SON), National Agency for Food and Drugs Administration and Control (NAFDAC) etcetera.
How did we get here?
Historicalcoincidences
As population increased, it became insufficient for the few importers to meet the import demands of the entire country. At about the same time, the country was making huge petro-dollars in oil revenues. As these monies began trickling into the society, more individuals found it attractive to venture into import businesses. This time may have also coincided with indigenization decree of 1970s when Nigerians began to take positions in the shipping/cargo trades. By this time, China was building its economy towards industrialization, surplus production and export drive. Today, they are the largest economy in the world!
Chinese producers brought greater flexibility in terms of pricing and quality which made them more attractive to many new importers than their European and American counterparts. This price-quality compromise made Chinese imports to Nigeria cheaper relative to others – exploiting the price sensitivity of consumers. This quality flexibility is most evident when one finds that an item produced in China for European or American markets tend to be more durable than those produced for Nigerian markets.
Regulatorylapses
Another explanation for the proliferation of substandard items is weak import regulation amplified by poor border management – corrupt border agents. In Nigeria today, anyone can import almost any item in commercial quantities so long as it is not in the contraband list or the few special goods that require import license. Times changed, the sector evolved but the regulatory framework has not changed. Just anybody should not be able to import goods in commercial quantities: it does not only make regulatory administration difficult especially for a highly populated country where there is personnel shortfall; it makes import demand for foreign currency becomes uncontrollable with attendant depreciation pressure on the local currency. In 2017 alone, import demand was NGN1.79 trillion, dwarfing the NGN720 set aside for Naira/Yuan swap for three years. On the production side, it cripples domestic ability to produce, leading therefore to output decline and unemployment.
eCommerce
One last factor was the internet and technology revolution. The development of internet technologies sparked irreversible revolution of trade through eCommerce, facilitating cross-border transactions such that everybody can buy virtually from any part of the world. This reduced the transport costs of business and eroded the market powers of the earlier importers. The importers market today, is purely competitive.
A simple way out
Admittedly, there have been major reforms to stem the tide such as anti-piracy technologies, raising penalties from 50,000 naira to 300,000 naira, and seeking collaborations with governments of trading nations. However, the fight must be strongest at home. It is therefore important to restrict commercial importing to registered importers and trading companies who meet certain criteria. These registration criteria need not be monetary payment but would include minimum capital requirements, loan credibility, storage/warehouse facilities, logistics ability and etcetera. The registration system would allow for efficient administration of regulatory checks on product quality and standards. The registered import businesses would be buoyant enough to issue product warranty and return guarantee should the product not satisfy the customer as against the current practice where consumers are ambushed by petty importers unable to give these assurances. So this would go a long way to ensure consumerism and consumer protection.
By way of trade protection, the registered importers would typically organize themselves into unions according to their respective trade lines and help combat substandard imports so as to protect their market profit and avoid regulators knocking their doors. The intuition is that these importers are better positioned to curb the menace of substandard items, and with the right incentives, would develop the internal interest to do so.
Regulatory agencies can then focus on design standards and compliance. Should any substandard product enter the local market, agencies would know where to begin their investigation. Inter-agency collaboration in order to avoid unhealthy rivalry and stakeholder engagement to bring about synergy in product tracking would help solve the lemons problem. As a final caveat, we are about signing the continental free trade agreement which opens our borders to a flood of importers from across Africa, if we cannot manage our own importers, what is to say we would be able to manage the multitude of African importers? Free trade does not mean dumping of substandard goods. We would more now than before, need a registry of importers.